Houston Flood Awareness for Home Buyers: Reading Maps, Disclosures, and Insurance
A practical guide for Houston-area buyers on where to check flood risk, what to ask about drainage and past flooding, and how flood insurance quotes can affect your monthly budget.
Why flood awareness matters when buying in Houston
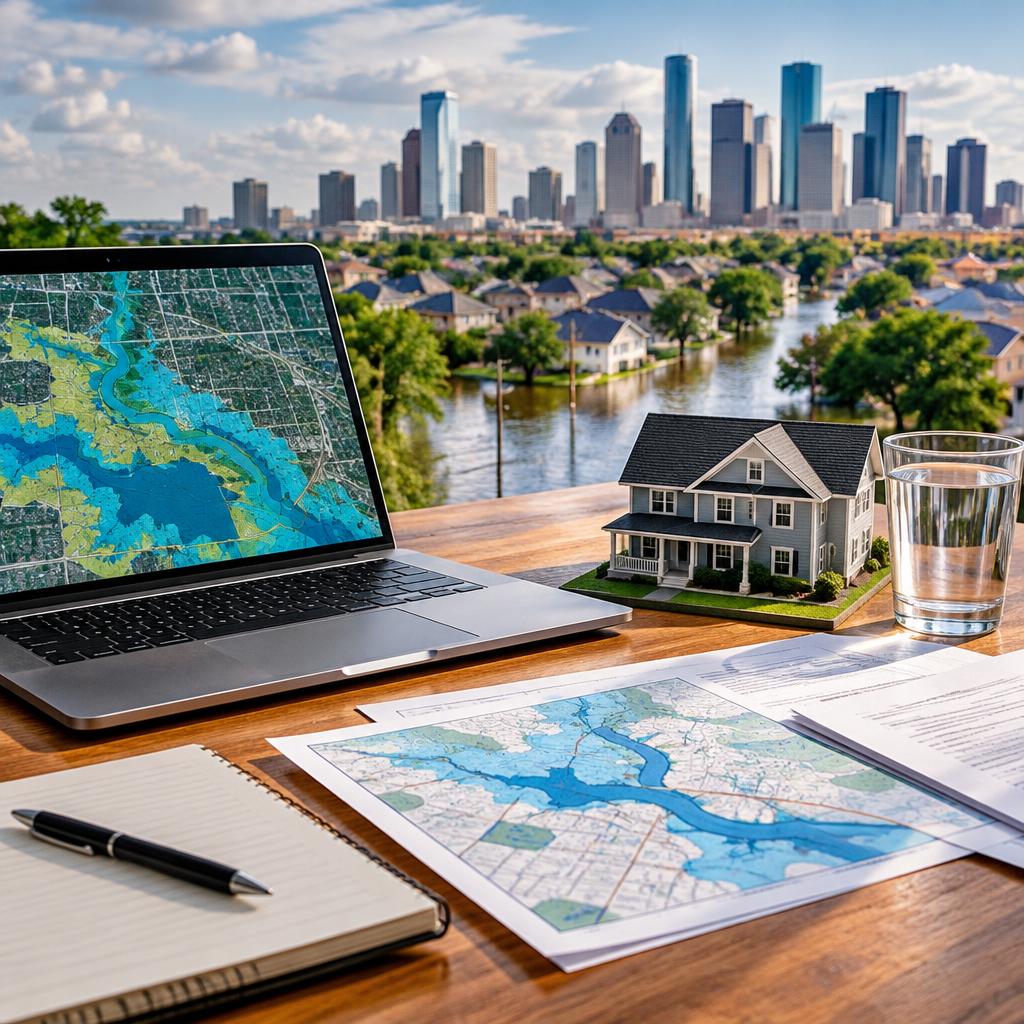
Houston’s climate and development patterns mean some neighborhoods are more prone to flooding than others. For a buyer, flood risk can affect safety, long-term maintenance, resale value, and monthly housing costs through insurance. Before you write an offer, it’s important to understand the local risk for the specific property you’re considering rather than relying on neighborhood reputation alone.
Where to check official flood maps
Start with official sources: the FEMA Flood Map Service Center for federal flood insurance zones and the Harris County Flood Control District or the city’s floodplain resources for local drainage and floodplain updates. Enter the property address on those sites to view the current Flood Insurance Rate Map (FIRM) and any local floodplain designations. Comparing both federal and local maps gives a fuller picture of regulatory zones and recent changes.
How to read common map labels and what they mean
Flood maps use zone labels that indicate different risk levels. High-risk coastal or river zones are often labeled VE or AE; these areas typically have higher insurance requirements and premiums. Shaded or unshaded X zones indicate lower relative risk, but not no risk. Maps also show base flood elevations (BFEs), which are used to set building standards and insurance rates. If a property sits at or below the BFE, expect higher insurance costs or mitigation requirements.
Key questions to ask and items to check in disclosures
Ask the seller or listing agent for any history of flooding, past insurance claims, and records of repairs or permits related to water damage. Confirm whether the property has an elevation certificate, a working sump or pump system, or recent drainage improvements. Review seller disclosures carefully for past flooding, foundation or slab work, and mold remediation. If disclosures are incomplete or vague, request more documentation or an inspection specific to water intrusion.
How flood insurance quotes affect your monthly budget
Flood insurance cost depends on zone designation, elevation relative to BFE, the building’s construction, and prior claims history. Lenders commonly require flood insurance for properties in high-risk zones; that requirement can add to your monthly housing cost. Get preliminary insurance quotes early—compare the National Flood Insurance Program (NFIP) options and private-market carriers when available—and factor premiums, deductibles, and coverage limits into your affordability calculations.
Practical due-diligence steps before you close
Order an elevation certificate if one isn’t available, arrange a property inspection that pays special attention to grading, gutters, and foundation drainage, and consider a specialist inspection for drainage or structural concerns. Check local permit records for past mitigation work, ask neighbors about their flooding experiences, and review any available claim history for the address. If significant risk is identified, consult with your lender and insurance agent about options and costs before committing.
How a local agent can help — and what to expect from your realtor
A local agent familiar with Houston’s neighborhoods can point you to the right maps and county resources, help interpret disclosures, and know which questions to raise with sellers and inspectors. Many clients appreciate an agent who listens and brings up concerns buyers might not think of; that hands-on guidance can make the due-diligence phase less stressful and more thorough. For buyers working with an agent, expect help coordinating document requests, insurance contacts, and inspectors.
Quick checklist for Houston home buyers
Before making an offer: look up the property on FEMA and local flood-control maps; ask the seller for flood-related disclosures and claim history; request or obtain an elevation certificate; get at least one flood insurance quote (NFIP and private if available); book a thorough inspection focused on drainage and water entry points; speak with neighbors about past events; and confirm lender requirements for insurance. These steps will help you evaluate risk and budget realistically for ownership.
Customer review
Article by
Tanya Makany
I have lived in this city all of my life and can tell you all about the great things this city has to offer. Houston is known for its great food, friendly people, and affordability. I have a background in communications, marketing and business. I have worked with people from all backgrounds and have a passion for helping others. My job is to treat you the way I would want to be treated. That means being responsive, honest and making the process as easy as possible. I am dedicated to helping you find the home of your dreams whether you are in the process of leasing, buying or selling, I am here to help!