Pasadena, TX Flood and Wind: What Your Home Insurance Does (and Doesn’t) Cover
A clear, practical guide for homeowners in Pasadena, La Porte, Channelview and nearby Harris County explaining the differences between standard homeowners insurance and separate flood or windstorm policies, common gaps in coverage, and steps you can take now to reduce risk.

Why this matters in coastal-adjacent communities
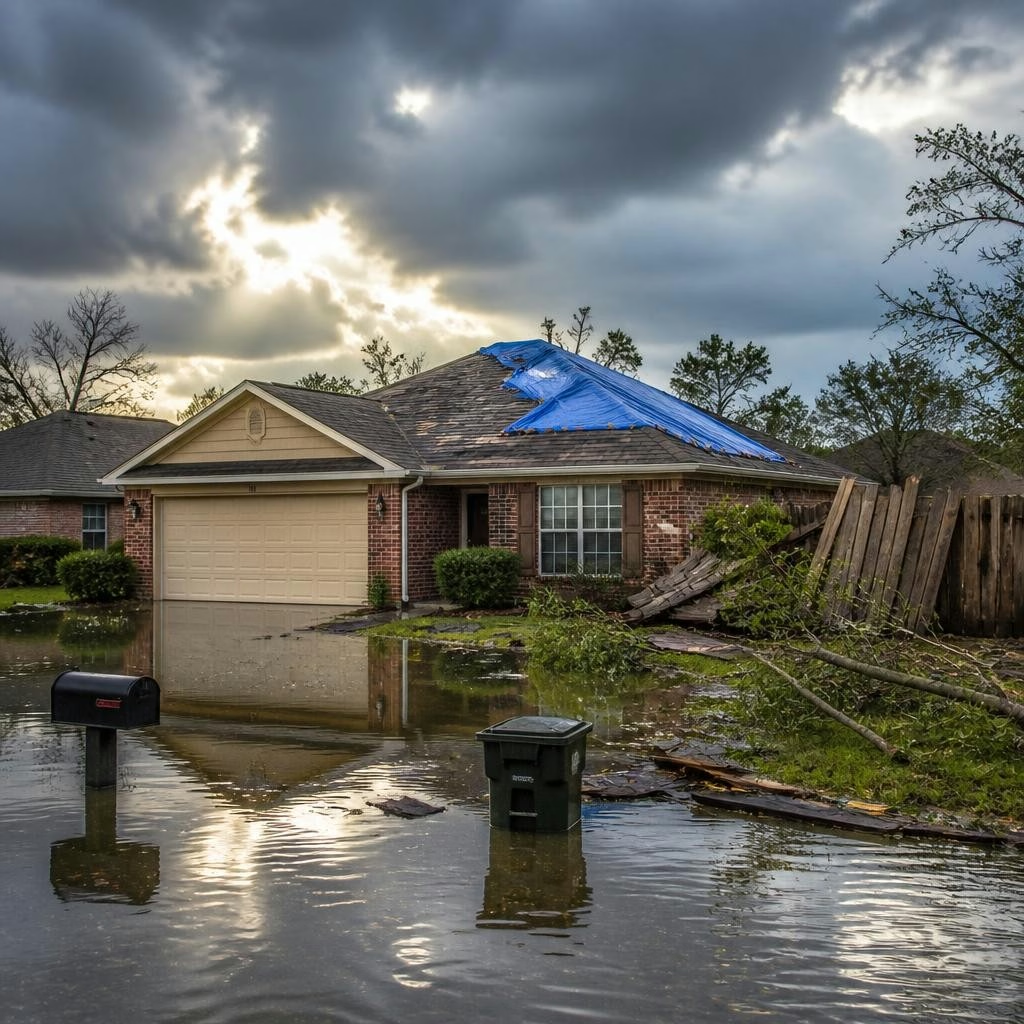
Pasadena, La Porte, Channelview and surrounding parts of Harris County sit close to the coast and are exposed to seasonal storms, heavy rains, and occasional hurricane impacts. That proximity affects the types of losses homeowners are most likely to face — and it also affects how insurance policies are written. This article explains what a typical homeowners policy usually covers, why flood and wind-related perils often require separate attention, and practical steps local homeowners can take to reduce financial and recovery risk.
What a standard homeowners policy generally covers
Most standard homeowners policies are designed to protect the structure of your home and your personal property from a range of common perils. Typical coverages include the dwelling (repairing or rebuilding your home after covered damage), other structures (like detached garages), personal property (furniture and belongings), personal liability (if someone is injured on your property) and additional living expenses (temporary housing if your home is uninhabitable). Coverage specifics and limits vary by insurer and policy form, so it’s important to review the declarations page to see exactly what is included.
Flood is usually excluded from homeowners insurance
A key point for coastal-adjacent homeowners: damage caused by flooding is commonly excluded from standard homeowners policies. 'Flood' generally refers to water that rises from the ground, such as storm surge, overflowing rivers, or surface water that enters the home from outside. If you live in a flood-prone zone or near tidal areas, a separate flood policy—through the National Flood Insurance Program (NFIP) or a private flood insurer—may be necessary to cover those losses.
Wind and hurricane-related coverage can be different
Wind damage is sometimes covered by a homeowners policy, but in coastal or hurricane-prone areas insurers often apply special conditions. These can include higher hurricane or windstorm deductibles, a separate named-storm deductible, or underwriting restrictions. In some cases an insurer may offer wind coverage as an endorsement or through a separate windstorm policy. Because practices vary by company and by property location, homeowners should confirm whether wind damage is covered, which deductible applies, and whether there are any policy exclusions for coastal addresses.
Common losses that homeowners may find are not covered
Beyond flood exclusion, there are several loss types that homeowners should watch for: routine wear and maintenance issues; seepage or gradual leaks that cause mold or rot; sewer or drain backups (often excluded unless you add a specific endorsement); and certain roof or siding damage if the insurer determines lack of maintenance contributed to the loss. Also note that coverage for contents and valuables can be limited; high-value items such as jewelry, fine art, and business equipment may require additional scheduled coverage.
Examples relevant to Pasadena, La Porte and Channelview
Practical examples illustrate the differences: if heavy rain causes a creek to overflow and water rises into your home, that is typically 'flood' and not covered by a standard homeowners policy. If a strong gust blows a tree limb through your roof, resulting damage to the structure and interior belongings is commonly covered under the dwelling and personal property sections, subject to deductibles. If hurricane surge pushes water into the house, that is usually flood-related; if high winds tear off shingles and rain enters through the roof, wind damage aspects may be covered while accompanying flood damage is not. Each claim situation is unique, so documentation and policy review are essential.
Practical steps to check and improve your protection
Start by reviewing your current policy’s declarations page, endorsements and deductibles. Confirm whether flood is excluded, whether you have a hurricane or windstorm deductible, and whether sewer backup or sump pump failure is included or available as an add-on. Determine whether your dwelling limit reflects replacement cost rather than actual cash value. If you’re uncertain about your flood zone, check FEMA’s flood maps for Harris County and ask your mortgage lender or local government for the most current designation. Consider elevating utilities, installing flood vents or a backflow valve, and maintaining roof and tree health to reduce the chance of avoidable claims.
How an independent broker like JAMCO Insurance can help
As an independent insurance broker serving Pasadena and nearby communities, JAMCO Insurance works with multiple carriers to compare options for homeowners, flood, and wind-related coverages. Brokers can identify whether your current insurer applies specific deductibles or exclusions for coastal exposures, locate flood insurance options (federal or private), and help assemble endorsements for items like sewer backup or scheduled valuables. Customers commonly note prompt, clear communication and help finding homeowner policies that fit their budgets and risk needs—an experience reflected in local feedback about the agency.
Documenting losses and navigating claims after a storm
If your home is damaged, act quickly to protect life and safety, then document the damage thoroughly with dated photos and video before making temporary repairs. Keep receipts for emergency work and store records off-site or in the cloud. Report the loss to your insurance agent or company promptly and ask about the insurer’s proof-of-loss requirements. JAMCO’s services include assistance with paperwork and filing claims, which can be helpful when an adjuster visit or documentation deadlines are involved.
Next steps and local resources
If you live in Pasadena, La Porte, Channelview or nearby Harris County communities, start by reviewing your policy and flood-zone status. Contact JAMCO Insurance for a free quote or a policy review to clarify flood exclusions, windstorm deductibles and available endorsements; their office is listed at 225 Preston Ave, Pasadena, TX. For flood-zone research and preparedness guidance, consult FEMA flood maps and your county emergency management resources. Preparing in advance, understanding your policy limits, and working with a broker who can compare carriers are practical steps that reduce uncertainty when storms arrive.
Customer review

Article by
JAMCO Insurance
We are an Independent Insurance Brokers that partner with Progressive, Allstate, Infinity, Kemper and many other companies. We provide free insurance quotes for auto, home, business & more.