Insurance for Landscaping, Cleaning, and Other Small Service Businesses in Pasadena, TX
A practical guide for solo and micro service businesses—landscapers, cleaners, handymen—covering the essential coverages, how to set limits, and how to work with an independent broker to secure the right policy for local jobsites.
Why a targeted approach to business insurance matters
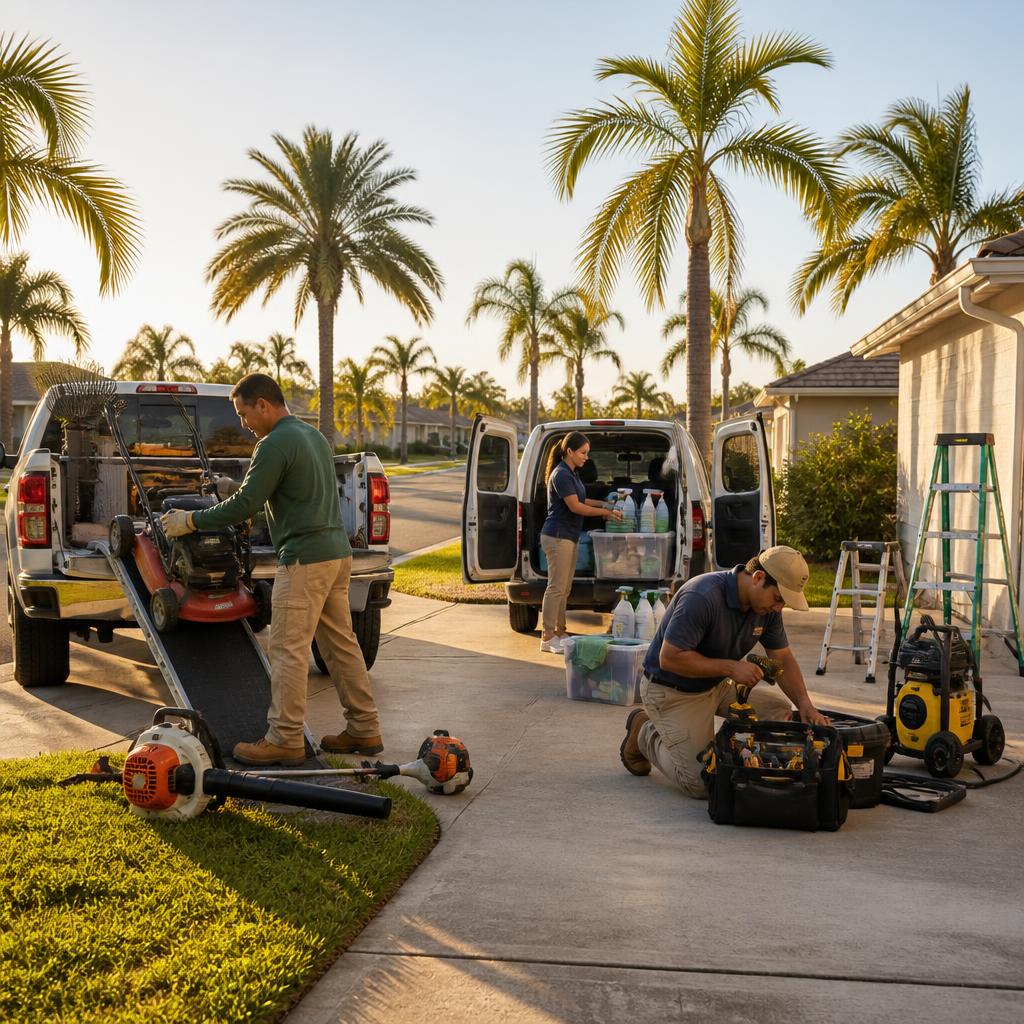
Micro and solo service businesses face a mix of everyday risks: on-site injuries, accidental property damage at clients' homes, loss or theft of tools, and liability from vehicles used for work. A focused insurance program helps protect your livelihood, keeps contracts intact, and addresses client requirements so you can concentrate on delivering services rather than absorbing unexpected loss.
General liability: the foundational coverage
General liability insurance is commonly the first policy small service businesses buy. It typically covers third‑party bodily injury and property damage that occur because of your operations—slips at a worksite, damage to a customer’s property while working, or claims of negligence. For many landscapers, cleaners, and handymen, this coverage is a contract and licensing requirement and provides an essential line of financial protection.
Commercial auto: covering work vehicles correctly
Personal auto policies usually exclude business use or provide limited coverage. If you use a vehicle to transport tools, haul debris, or travel between jobs, commercial auto coverage bridges that gap. It protects against liability for accidents involving work vehicles and can include physical damage (collision/comprehensive) for owned vehicles used in the business.
Tools and equipment coverage: protect what you can’t afford to replace
Portable tools and small equipment are the backbone of solo service businesses. Tools and equipment coverage (sometimes called inland marine or equipment floater) can reimburse you if those items are stolen, lost, or damaged on a jobsite or in transit. When deciding limits, inventory high‑value items and consider replacement cost versus actual cash value.
Contract exposures and certificates of insurance
Many clients, property managers, and subcontractors will ask for a certificate of insurance (COI) before you begin work. Common contractual requirements include specific liability limits and additional insured endorsements. Having a broker who can prepare COIs and explain contractual language can save time and prevent work delays—especially when deadlines and permit requirements are involved.
Choosing limits and deductibles for small operations
Limit and deductible choices balance cost and protection. For general liability, many small service businesses begin with standard limits that satisfy client contracts and scale up if they handle higher‑value properties or more hazardous work. Deductibles on property and equipment coverages should reflect how much out‑of‑pocket expense you can absorb after a loss. Discuss recent job sizes, highest exposure scenarios, and any client requirements with your agent to tailor limits appropriately.
When to consider a package policy or additional endorsements
Depending on your operations, a packaged policy or endorsements can provide a simpler, often cost‑effective way to combine core coverages. Examples include bundling liability with equipment coverage or adding hired/non‑owned auto coverage if you use subcontractors’ vehicles. An independent broker can compare available options and explain trade‑offs so you don’t buy overlap or leave gaps.
How an independent broker can help you shop smarter
Independent insurance brokers work with multiple carriers to find coverage that fits your budget and risk profile. JAMCO Insurance, for example, partners with carriers such as Progressive, Allstate, Infinity, and Kemper and provides free quotes for business coverages. Customers frequently note that knowledgeable agents can simplify the process of matching the right type and level of coverage to small service operations.
What to expect from the application and servicing process
A good broker will ask about your specific operations, job frequency, vehicle use, and tools inventory; help complete applications; and provide required paperwork like COIs. Reviews and client feedback emphasize responsiveness and clear communication as valuable qualities—timely answers to questions and straightforward renewal support reduce administrative burden for busy owners. JAMCO lists services such as insurance consultation and paperwork assistance to support these needs.
Practical next steps and local contact details
Start with a simple checklist: list the vehicles and tools you use for work, note typical job locations and client requirements, and gather any current insurance documents or contracts that mention insurance. Then request quotes and COI samples from a broker so you can compare coverage language and limits, not just price. For businesses in the Pasadena and greater Harris County area, JAMCO Insurance is located at 225 Preston Ave, Pasadena, TX, and serves nearby communities including Pasadena, Houston, Deer Park, Channelview, and La Porte. Asking for multiple quotes and assistance with certificates will help you meet client conditions and protect your business as it grows.
Customer review
Article by
JAMCO Insurance
We are an Independent Insurance Brokers that partner with Progressive, Allstate, Infinity, Kemper and many other companies. We provide free insurance quotes for auto, home, business & more.