Certificate of Insurance 101 for Houston-Area Contractors: How to Avoid Job Delays
A practical guide for contractors working around Pasadena and greater Houston explaining what a Certificate of Insurance (COI) is, common requirements from GCs and property managers, how to request one correctly from your broker, and the frequent mistakes that lead to project or payment delays.
Why COIs matter for contractors in the Houston area
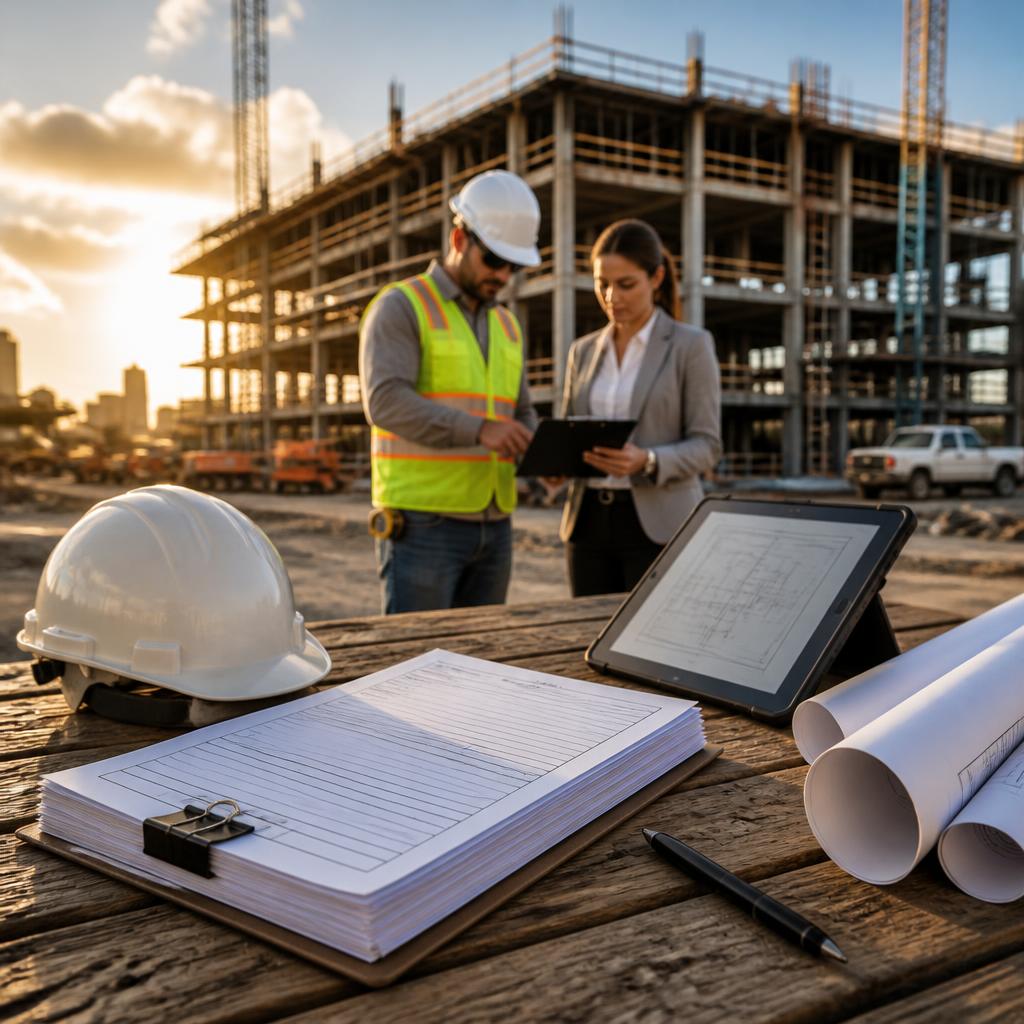
A Certificate of Insurance (COI) is the standard document general contractors, property managers, and owners use to confirm a subcontractor or vendor has the insurance the job requires. For contractors working in Pasadena, Houston, Deer Park and surrounding parts of Harris County, an accurate COI keeps projects moving, protects contract payments, and reduces the chance of being turned away at a jobsite. Treating COI requests as part of project administration — not an afterthought — is the best way to avoid costly delays.
What a COI shows (and what it doesn’t)
A COI summarizes key facts about an insurance policy: the carrier, policy number, effective and expiration dates, the types of coverage in force (for example, general liability, commercial auto, or workers’ compensation), and the policy limits. It also lists the certificate holder and any named additional insureds. A COI is not a full policy and does not include the contract language or policy provisions themselves; some owners and GCs will request endorsements or a declarations page in addition to the COI to confirm specific contractual provisions.
Typical requirements from GCs and property managers
Requirements vary by project size and owner, but contractors should expect to be asked for: proof of commercial general liability, commercial auto (if vehicles will be on site), and workers’ compensation where required by law. Many property managers and general contractors also insist on having the owner or GC named as an additional insured and may require endorsements such as primary/noncontributory wording or a waiver of subrogation. Because requirements differ by job, always review the contract and any attached insurance exhibit before requesting a certificate.
Who should be listed on the COI and how to phrase it
Common items asked for on a COI include the certificate holder (the company or owner who will receive the COI) and any additional insureds (often the general contractor or property manager). The best practice is to provide the exact legal name and mailing address for the certificate holder, plus any specific additional insured language the contract requires. Vague or incomplete names are a frequent cause of rejection; if the contract lists a company’s DBA or an LLC, provide that exact designation to your broker.
How to request a COI correctly from your broker
When requesting a COI, provide your broker with the full contract insurance exhibit, the project name and address, the certificate holder contact and address, and any required additional insured or waiver language. If an endorsement form is specified, attach it. JAMCO Insurance, as an independent broker working with multiple carriers, can prepare COIs and coordinate endorsements when needed — and many customers report timely, knowledgeable assistance from our commercial team. Supplying complete, accurate information up front allows the broker to deliver the right certificate the first time.
Common mistakes that cause project or payment delays
Several recurring errors lead to delays: submitting the wrong certificate holder name; requesting a COI with incorrect effective dates; failing to request required endorsements; asking for personal auto coverage instead of commercial auto; or providing an incomplete contract exhibit. Administrative oversights — such as missing project addresses or not specifying the scope of work on the COI — also cause hold-ups. Anticipate requirements early and confirm them with the GC or property manager rather than assuming standard language will suffice.
When an endorsement or policy evidence is required
Some owners will not accept a COI alone and will ask for specific endorsements (for example, additional insured endorsements or primary/noncontributory forms) or a declaration page. If the contract calls for named endorsements, request those up front from your broker. Endorsement forms must come from the insurer and can take extra processing time, so include this need in your schedule and make the request before mobilizing crews to the site.
A practical checklist to hand your broker
To streamline the process, prepare a short checklist you can send to your broker with each COI request: 1) Contract insurance exhibit attached; 2) Exact certificate holder name and address; 3) Project name and physical address; 4) Any required additional insured wording or endorsement forms; 5) Desired delivery method (email or fax) and recipient contact; 6) Desired effective date and any start-of-work deadlines. Delivering a complete checklist reduces back-and-forth and shortens turnaround time.
How JAMCO’s services support COI needs
As an independent broker working with multiple carriers, JAMCO Insurance can help contractors obtain the types of commercial coverage commonly required on Houston-area jobs and prepare COIs and endorsements when requested. Services listed by the agency — including insurance consultation and paperwork assistance — are relevant to contractors who need help interpreting contract language or coordinating with carriers. Customers frequently praise the staff’s responsiveness and commercial insurance knowledge, which is especially useful when deadlines are tight.
Final tips to avoid COI-related job delays
Start the COI process early — ideally when you sign the subcontract or at bid acceptance — and confirm exact insurance language with the GC or property manager. Keep a digital copy of commonly requested endorsements and maintain a direct line to your broker for urgent requests. If a certificate is rejected, ask for the specific reason in writing so corrections are precise. When managed proactively, COI administration becomes a routine part of project setup rather than a source of last-minute delays.
Customer review
Article by
JAMCO Insurance
We are an Independent Insurance Brokers that partner with Progressive, Allstate, Infinity, Kemper and many other companies. We provide free insurance quotes for auto, home, business & more.