How Baton Rouge Renters Can Protect Belongings From Theft, Fire, and Water Damage
A practical guide for renters in Baton Rouge explaining common apartment risks, how renters insurance typically responds to theft, fire, and water damage, what is usually excluded, and how to set realistic coverage limits.
Why this matters for Baton Rouge renters
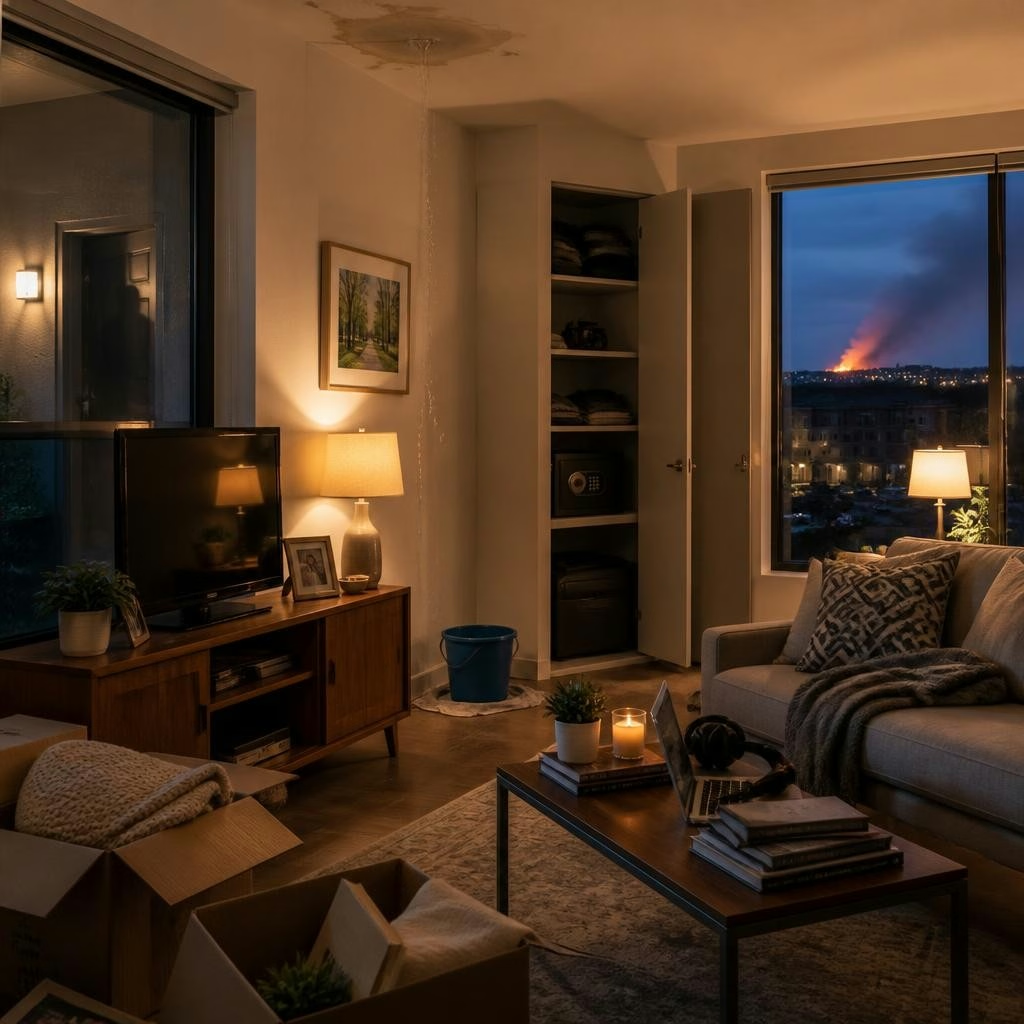
Renters in Baton Rouge face a mix of everyday and weather-related risks: break-ins, apartment fires, frozen or burst pipes, and storm-related water problems. Protecting your personal property and arranging liability coverage are practical steps you can take now to reduce stress and financial loss if the unexpected happens.
The most common scenarios: theft, fire, and water
Theft and burglaries can occur in apartments and multi-unit buildings. Fires—caused by cooking accidents, electrical faults, or heating equipment—can destroy belongings and force temporary relocation. Water damage appears in different forms: sudden events such as a burst pipe or appliance failure, and slower problems like persistent leaks, sewer backups, or flooding after heavy storms. Each of these has different implications for insurance coverage.
What renters insurance typically covers
Standard renters insurance policies generally cover three core areas: personal property (your belongings), personal liability (if someone is injured in your rented home), and additional living expenses (costs to live elsewhere temporarily if your unit becomes uninhabitable). For property losses, many policies respond to named perils such as theft and fire, and they often cover sudden, accidental water damage like a burst pipe. Policy language varies, so review the specifics to know which perils are covered.
What is usually excluded or limited
Some types of loss are commonly excluded or require an endorsement: flood damage from rising water due to storms or river overflow is typically not covered by renters insurance and requires separate flood insurance; gradual seepage, long-term mold, or deterioration may also be excluded; sewer backups and sump pump failures are often excluded unless you add a specific endorsement. High-value items—jewelry, fine art, collectibles—are often subject to sub-limits and may need a scheduled personal property endorsement to be fully protected.
How to set realistic coverage limits
Start with a room-by-room inventory: list major items, note purchase prices or current replacement costs, and collect receipts or photos. Use online prices when receipts are unavailable and be conservative in your estimates to avoid underinsurance. Choose a contents limit that reflects replacement cost, not just sentimental value, and review it annually or after major purchases. If you own high-value items, consider scheduling them separately rather than relying on the policy’s standard sub-limits.
Deductibles and valuation methods: what to consider
Policies may settle claims on an actual cash value (ACV) basis—replacement cost minus depreciation—or on a replacement cost basis that covers the full cost to replace an item. Replacement cost coverage is more protective but usually costs more. Higher deductibles lower premiums but increase your out-of-pocket expense when you file a claim. Ask an agent to show both ACV and replacement cost scenarios so you can choose the balance that fits your budget and risk tolerance.
Practical steps to reduce risk at home
Prevention lowers both the chance of a loss and the size of potential claims. Keep doors and windows locked, use deadbolts and secure sliding doors, and consider a home alarm or motion lights. Maintain smoke and carbon monoxide detectors and test them regularly. Report plumbing issues to your landlord promptly; many water losses start with minor problems that escalate. Store irreplaceable documents and expensive jewelry in a safe or safety deposit box, and keep digital copies of receipts and photos offsite or in the cloud.
Getting the right policy and local help
An experienced local agent can clarify policy language, suggest needed endorsements (for example, sewer-backup or higher limits on valuables), and help you compare replacement cost versus ACV options. Morris Insurance Group offers renters insurance and can also assist with flood insurance options if needed. Customers regularly note helpful, attentive service and assistance finding appropriate coverage and competitive rates, and one customer specifically reported receiving very good rates and responsive support when shopping for renters and auto coverage. For a free quote or a policy review, you can call or use the online form, or visit the Baton Rouge office at 2431 South Acadian Thruway Suite 290 to discuss your needs in person.
Customer review
Article by
Morris Insurance Group
Morris Insurance Group, based in Baton Rouge, offers a range of affordable insurance for your auto, home, and business. For a quick, free insurance quote, call today, fill out a quote form online, or stop by our office off College Drive. Let us help you protect what's yours.