Insurance Checklist for Small Businesses in Katy, Sugar Land, and Cypress
A concise, practical checklist of essential insurance coverages and local considerations for small businesses in Katy, Sugar Land, and Cypress, with examples for shops, contractors, and home-based operations and next steps to obtain quotes.
Why a local insurance checklist matters
Small businesses in the Katy, Sugar Land and Cypress area face a mix of exposures—physical property, customer interactions, commercial driving and weather events such as flooding. A focused checklist helps owners identify the coverages that matter for their specific operations and avoid gaps that can interrupt business or create unexpected liability. As independent insurance brokers, JAMCO Insurance - Johanna Munoz works with multiple carriers to produce comparative quotes for auto, home and business coverages, which helps local owners evaluate options that suit regional risks and budgets.
Essential coverages to review
Start with these core policies and endorsements, tailoring each to your business size and activity: general liability to protect against third‑party bodily injury and property damage; commercial auto coverage for vehicles used to transport goods, make service calls or carry customers; business or commercial property insurance to cover buildings, inventory and equipment; and flood insurance when your premises or stored property are at risk from heavy rains and storm surge. For many small operations, a Business Owners Policy (BOP) that combines liability and property elements can be cost‑effective—discuss whether a BOP fits your exposures. Because JAMCO lists flood coverage among its services and can source auto and business quotes, these are logical starting points when requesting proposals.
Examples by type of small business
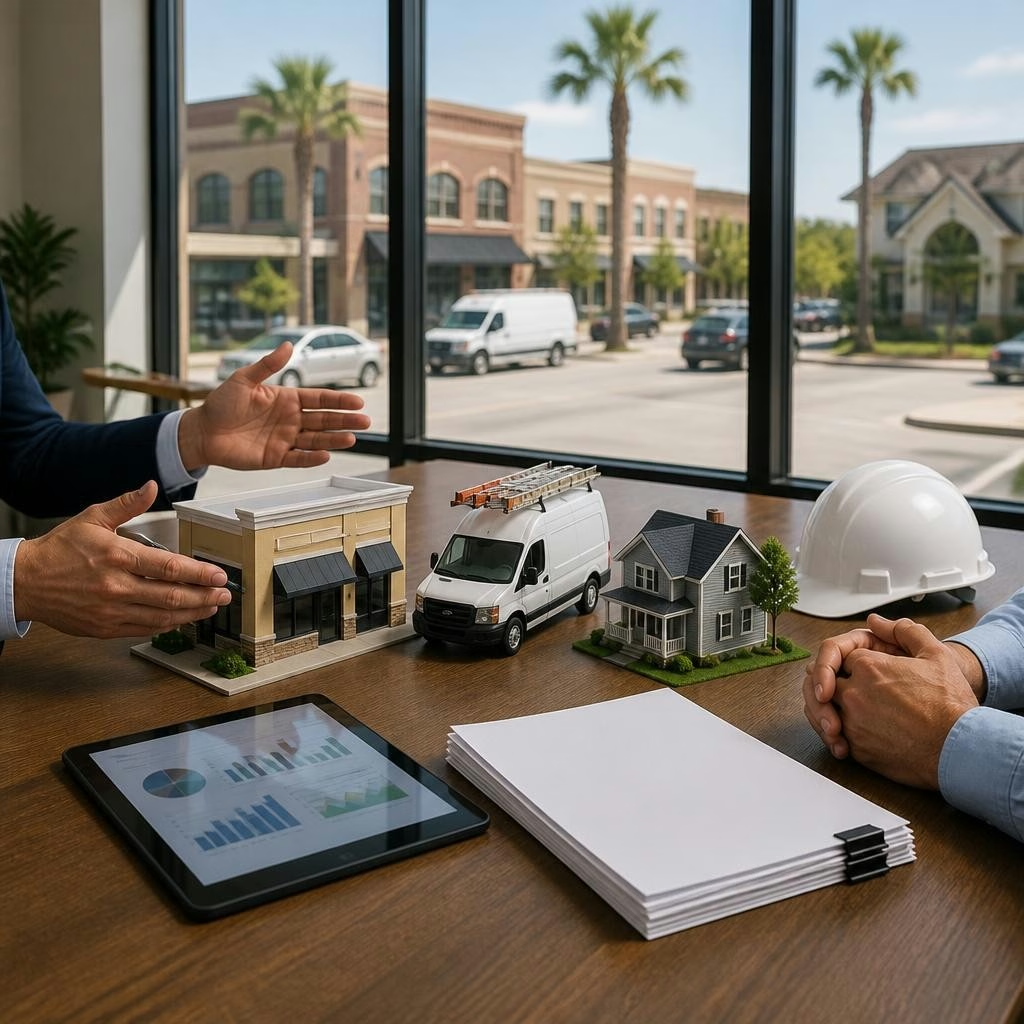
Retail shop: prioritize property coverage for inventory, general liability for customers on premises, and commercial auto if you offer deliveries. Contractor or trades business: emphasize commercial auto for service vehicles, liability for on‑site work, and tools/equipment coverage to protect mobile assets. Home‑based business: ensure your homeowners or renters policy is evaluated for business content limits and consider a business contents endorsement or standalone business property policy if you keep significant equipment or inventory at home. These examples illustrate common exposure patterns; your exact needs will depend on operations, premises and whether staff or subcontractors are involved.
How to get started and next steps
Prepare a brief summary of your business operations (type of work, number of employees, list of vehicles, value of stock and equipment, and physical address) and request written quotes from an independent broker. JAMCO Insurance - Johanna Munoz can obtain multiple quotes from carriers it represents to help compare coverage limits, exclusions and premiums for businesses in Katy, Sugar Land and Cypress. Review policies annually or after major changes—new vehicles, increased inventory, or changes to the scope of services—to keep your protection aligned with current risks. Contact the agency for a free consultation and to discuss which combinations of coverages make sense for your business profile.
Article by
JAMCO Insurance - Johanna Munoz
Somos corredores de seguros independientes asociados con Progressive, Allstate, Infinity, Kemper y muchas otras compañías. Ofrecemos cotizaciones de seguros gratuitas para automóviles, viviendas, negocios y más.