Do You Need Flood Insurance in Katy or Houston If You’re Not in a Flood Zone?
An accessible explanation of how flood zones work in the Katy–Houston area, when homeowners outside high-risk zones should consider flood insurance, what a separate flood policy covers versus a standard home policy, and practical next steps to get a quote.
Why flood insurance is worth considering locally
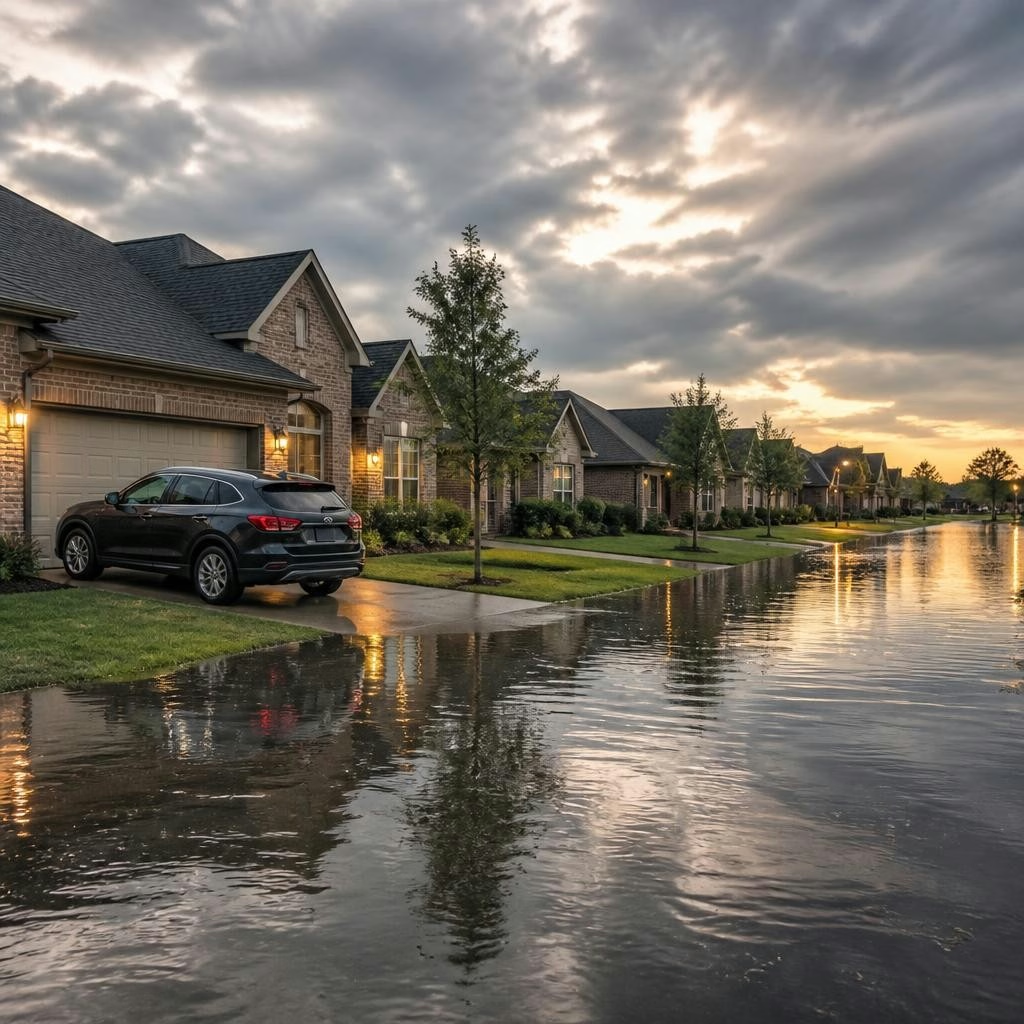
Katy and greater Houston sit in a region where heavy rain, storm surge, and localized drainage issues can cause flooding. Being labeled “not in a flood zone” on a map does not eliminate the risk of water damage from intense storms, nearby bayous or poor drainage after heavy rainfall. For homeowners and business owners, the potential cost of flood repairs can be large; that is why many people evaluate flood insurance as a risk-management step even when a property is outside FEMA’s high-risk designation.
How flood zones and maps work
Flood zone designations come from FEMA flood maps (FIRMs) and are used by lenders and insurers to assess risk. Zones identified as high-risk (Special Flood Hazard Areas) often trigger mandatory flood insurance requirements for properties with federally backed mortgages. Other zones are classified as moderate- or low-risk. These maps are updated periodically and represent a modeled risk based on historical data and topography; they do not guarantee that flooding will or will not occur at a specific address.
When to buy flood insurance even if you’re not in a high-risk zone
Consider flood coverage if your property is: near creeks, bayous, drainage channels, or stormwater outfalls; at a low elevation relative to surrounding streets; in a neighborhood that has flooded previously; or if you have a finished basement or valuable contents susceptible to water damage. Also weigh lender requirements and personal tolerance for financial risk: even properties in moderate- or low-risk zones have experienced flood losses after extreme weather. Remember, flood policies are separate from standard homeowners insurance and may have a policy waiting period before they take effect, so plan ahead rather than waiting until a storm is imminent.
What a flood policy covers, and next steps with JAMCO Insurance
A separate flood policy typically covers direct physical damage to your building and, depending on the policy, your personal property from flooding. Standard homeowners policies generally exclude flood damage, so adding a flood policy is the main way to secure coverage for those perils. If you’re in Katy, Houston, Sugar Land, Cypress or nearby areas and would like to review options, JAMCO Insurance - Johanna Munoz can provide free flood-coverage quotes and explain available private and NFIP alternatives. Start by checking your property’s current flood map designation, make an inventory of at-risk features (basement, proximity to waterways), and contact an agent to compare policy limits, deductibles, and any waiting periods that may apply.
Article by
JAMCO Insurance - Johanna Munoz
Somos corredores de seguros independientes asociados con Progressive, Allstate, Infinity, Kemper y muchas otras compañías. Ofrecemos cotizaciones de seguros gratuitas para automóviles, viviendas, negocios y más.