Storms, Flooding, and Hail: How Houston Weather Should Shape Your Auto Insurance Coverage
A practical guide for Houston-area drivers explaining how heavy rain, flooding, hail and hurricanes commonly affect vehicles, why comprehensive and related coverages matter, and how to tailor a policy to local weather risks.

Why Houston weather matters for your auto insurance
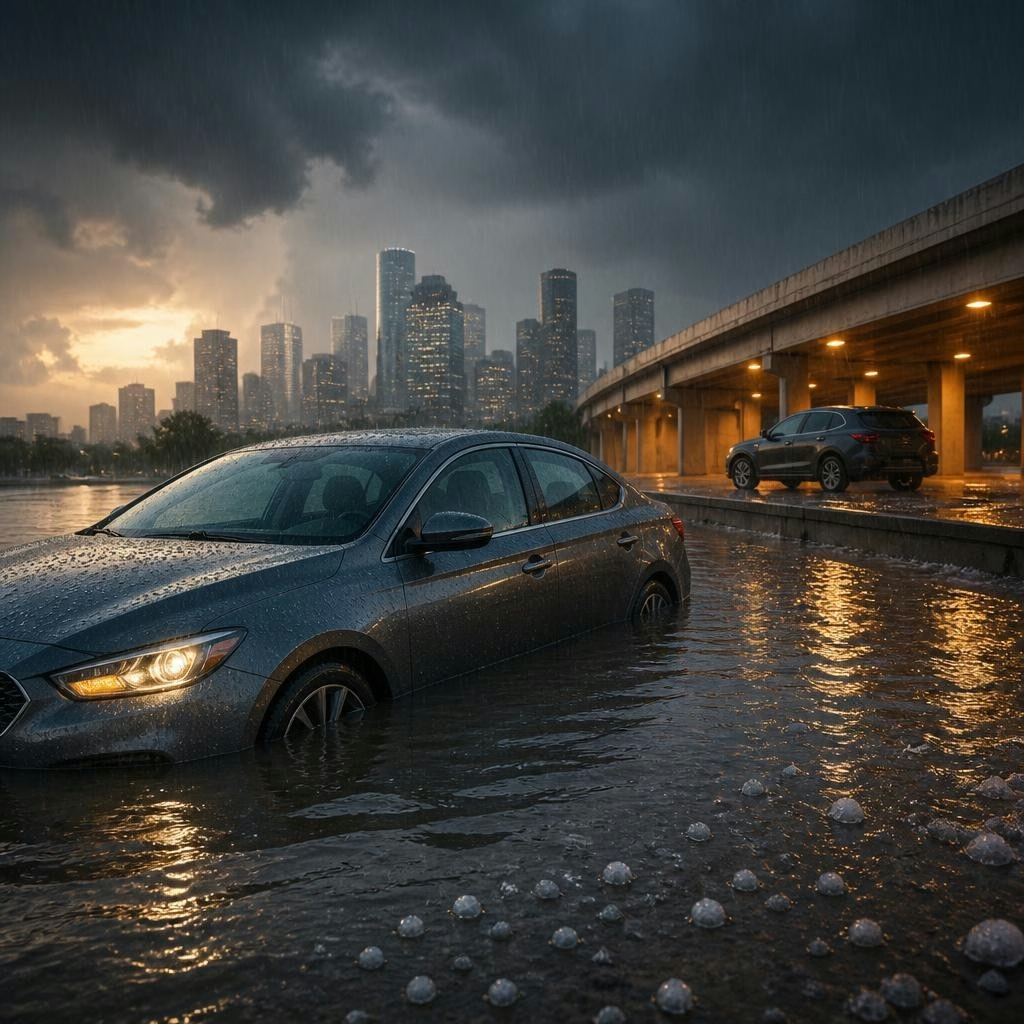
Houston and the surrounding areas regularly experience heavy rain, flash flooding, hailstorms and the occasional hurricane. These events create distinct risks for vehicles: water intrusion, hail dents and broken glass, wind-driven debris damage, and increased chances of collisions during severe weather. Understanding how these perils interact with typical auto coverages helps drivers choose the protections that fit their exposure and budget.
Common weather damage and how it happens
Heavy rain and street flooding can submerge engines and interiors, causing electrical and mechanical failures that are expensive to repair. Hail can dent body panels and shatter windows. Hurricanes and strong thunderstorms can lead to windborne debris, falling trees, and power loss that increases the risk of accidents while traveling. Recognizing the ways weather damages vehicles makes it easier to prioritize the right coverages and take preventive steps.
Comprehensive coverage: the cornerstone for weather-related loss
Comprehensive coverage typically applies to non-collision events such as hail, wind, and many types of flood or water-related damage. Adding comprehensive protection means your insurer may cover repairs or replacement when a storm damages your vehicle—subject to policy terms and your deductible. Because policies vary, confirm with your broker or carrier whether specific events (for example, flood-related engine failure) are included and whether any endorsements or exclusions apply.
When standard policies don’t cover flood damage
Not every policy treats flood the same way, and there are situations where repair costs exceed what a typical auto policy will handle. For example, damage from rising water might be covered under comprehensive in many policies, but insureds should verify limits, deductibles and any exclusions. In areas with repeated flooding, drivers may need to weigh higher coverage limits or consider additional safeguards such as parking in higher locations during storm warnings.
Hail, glass, and targeted endorsements
Hail frequently causes cosmetic damage and cracked windshields. Some insurers offer glass-specific coverages or lower deductibles for glass repairs so you aren’t forced to pay a large out-of-pocket amount for a windshield replacement. If you live in hail-prone neighborhoods around Houston, ask about glass claims handling, repair network options, and whether a separate deductible applies for glass or comprehensive claims.
Practical steps before, during, and after a storm
Preparation reduces loss and speeds recovery. Before a storm: move vehicles to covered or higher ground when possible, secure loose items and take dated photos of your car’s condition. During a storm: avoid driving through standing water—don’t underestimate it—and never start a submerged vehicle. After a storm: document damage with photos, note approximate water depth and location, and contact your broker or insurer promptly to report the claim. Quick reporting helps preserve evidence and can speed repairs.
Tailoring your policy to local risks
Decisions about deductibles, coverage limits and optional add-ons should reflect how and where you park, commute routes and whether the vehicle is financed. Lower comprehensive deductibles reduce out-of-pocket costs after storm damage but raise premiums; higher deductibles lower premiums but shift risk to you. Optional protections to discuss with an independent broker include glass endorsements, rental reimbursement while your vehicle is repaired, and towing or roadside assistance—services that can be particularly valuable after severe weather events.
How an independent broker can help you prepare
As an independent insurance broker working with carriers such as Progressive, Allstate, Infinity and Kemper, JAMCO Insurance - Robert Goodwin can compare available auto policies and point out differences in how carriers handle hail, flood and hurricane-related claims. A broker can review your current coverage, explain exclusions and deductibles in plain terms, and suggest adjustments that reflect Houston-area weather risks. If storm season is approaching, contact your broker to review options and ensure your policy matches your exposure.
Article by
JAMCO Insurance - Robert Goodwin
I'm an Independent Insurance Broker that partner with Progressive, Allstate, Infinity, Kemper and many other companies. We provide free insurance quotes for auto, home, business & more