What Houston Homeowners Should Know About Storm and Wind Damage Coverage
A practical guide for Houston-area homeowners explaining how standard home insurance typically handles wind, hail, and storm damage, common exclusions to watch for, and the key questions to ask an insurance agent before and after severe weather.
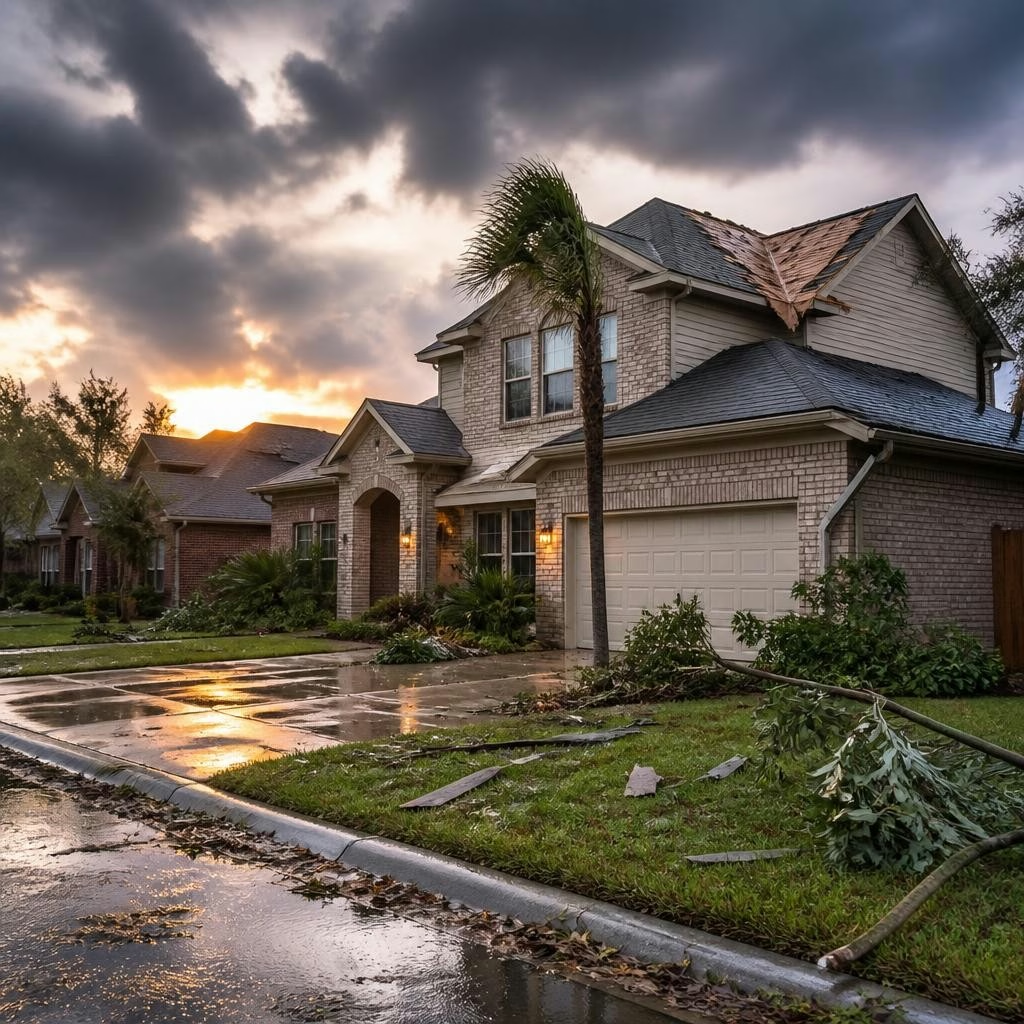
Why storm and wind coverage matters in Houston
Houston homeowners face a higher-than-average chance of severe thunderstorms, hail events, and tropical systems that bring damaging wind. Understanding how your policy responds to wind and hail losses — and where it does not — helps reduce surprise expenses and speeds recovery after an event. Because flood damage and wind-related damage are treated differently by insurers, reviewing your coverages ahead of storm season is especially important in the Houston area.
How standard home insurance typically handles wind and hail
Most standard homeowner policies provide dwelling coverage that applies when wind or hail causes sudden physical damage to the structure. Coverage for other structures (sheds, fences) and personal property is usually included but subject to limits. Many policies also offer additional living expense coverage to help with temporary housing if a covered loss makes your home uninhabitable. Exact terms and limits vary by insurer and policy form, so the general principle is: sudden wind and hail damage is often covered, but the scope and payout depend on your specific policy language.
Common exclusions and limitations to watch for
There are several common policy exclusions and limitations that can leave homeowners exposed after a storm. Flood is typically excluded from standard homeowner policies and requires a separate flood policy. Some policies exclude damage caused by poor maintenance, wear and tear, or pre-existing conditions. Additionally, certain properties in high-risk or coastal areas may face windstorm exclusions or different rules for named storms. Read your declarations page and exclusions carefully to see if any of these apply to your property.
Windstorm deductibles and special provisions
Insurers sometimes apply a separate wind or hurricane deductible for wind-related losses rather than the standard deductible shown for other perils. In some areas, that deductible is calculated as a percentage of dwelling coverage rather than a flat dollar amount. The result can be a higher out-of-pocket cost after a storm. Because practices differ among carriers, confirm with your agent whether a special wind/hurricane deductible applies and how it would be calculated for your home.
Replacement cost versus actual cash value
Whether your policy pays replacement cost or actual cash value for damaged property affects how much you’ll receive on a claim. Replacement cost covers the expense to repair or replace items without deduction for depreciation, while actual cash value reduces the payout to account for age and wear. Many homeowners choose replacement-cost coverage for dwelling and major personal property, but this choice typically affects premiums. Ask your agent which valuation method applies to your dwelling, other structures, and contents.
Practical steps to prepare before a storm and handle claims after
Before severe weather arrives, document your home with date-stamped photos or video, secure loose outdoor items, and trim trees that could fall on structures. Keep an inventory of high-value items and store policy documents in a safe, accessible place. After a storm, prioritize safety, make temporary repairs to prevent further loss (keep receipts), and report claims promptly. When meeting with contractors or adjusters, keep records of estimates, communications, and receipts to streamline the claims process.
Key questions to ask your insurance agent
When reviewing coverage, ask clear, specific questions: Does my policy cover wind and hail damage to the dwelling, other structures, and contents? Is there a separate wind or hurricane deductible, and how is it calculated? Do I have replacement-cost or actual-cash-value coverage? Is flood damage covered or do I need a separate policy? Are there endorsements or riders I should consider for high-value items or roof/hail protection? What is the claims process and typical timeline with the carriers you work with? These questions help you compare options and identify gaps before a storm.
How an independent broker can help and next steps
As an independent insurance broker based in Houston, JAMCO Insurance - Donald R. Idlebird partners with multiple carriers to compare options for home coverage, including companies such as Progressive, Allstate, Infinity, and Kemper. We can review your current policy, explain any wind or hail deductibles and exclusions, outline options for replacement-cost coverage or endorsements, and provide free quotes tailored to your property and risk profile. Contact a broker to schedule a policy review before storm season so you can make informed decisions and reduce surprises after severe weather.
Article by
JAMCO Insurance - Donald Idlebird
I'm an Independent Insurance Brokers that partner with Progressive, Allstate, Infinity, Kemper and many other companies. We provide free insurance quotes for auto, home, business & more. Located in Houston, TX. We’re here to help protect you from the unexpected and plan for the predictable. Get in touch with one of our insurance agents today!